Long Term Care Insurance
The real risk isn't needing care. It's not having a plan for it.
A health change can undo decades of careful
retirement planning in a matter of months.
"When my father had dementia, I saw firsthand how quickly
it can impact family relationships and their finances."
— Ivory Johnson, CFP®, ChFC
1 in 9 people age 65 and older has Alzheimer's.
It's why Ivory wrote"An Alzheimer's Wave Is Coming," published in CNBC— and why he built his practice
around planning for this before a crisis forces the decision.
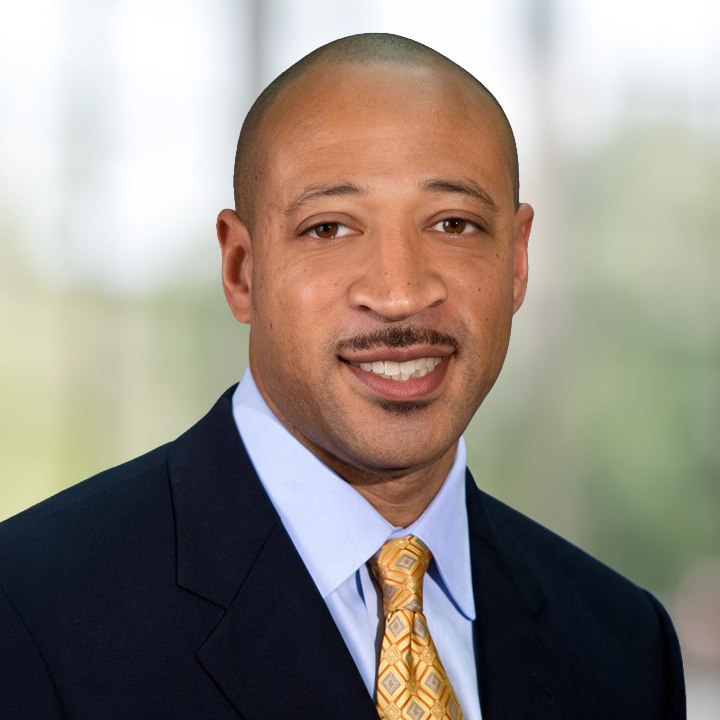
Ivory Johnson, CFP®, ChFC
Delancey Wealth Management
After watching his father go from doing his own taxes to not recognizing his own children, Ivory became passionate about helping families plan for the possibility of long-term care. With over 30 years of financial planning experience, Ivory is an independent advisor and isn't tied to one insurance company or one type of policy.
His goal on a call with you: help you understand your real options, not sell you the one his firm makes the most on.
The question isn't whether you'll need long-term care;
it's how you'll pay for it.
Some families choose insurance. Others choose a hybrid strategy or decide to self-insure.
The right answer depends on your health, assets, income, family circumstances and retirement goals.
The Traditional Path
A dedicated long-term care policy: its own premium, its own medical qualification, coverage that activates when you need it.
Often the most direct option — premiums can rise over time and you may pay in for years without ever using it.
The Hybrid Path
Life insurance with a long-term care feature built in. Access funds early if you need care, or leave the death benefit intact if you don't.
Premiums are generally fixed, but total cost usually runs higher than the traditional path.
The Built-in Path
Care coverage built into your retirement income itself — no separate premium, no medical exam beyond what your plan already requires.
Works within a plan you likely already have, rather than adding a new one.
The retirement planning
guide to long-term care
A practical roadmap families can work through on their own time, before any conversation with an advisor.
What's Inside
- The key legal documents to have in place
- What care actually costs, by setting and region
- How Medicare and Medicaid do — and don't — help
- Notes on caregiver support and fraud prevention
- A 30-day action plan you can start this week
Free PDF. No obligation to talk to anyone.
Common Questions
Which of these three paths is right for me?
It depends on your health, your finances, and your priorities; there's no universal answer. That's exactly what the consultation is for.
I don't want a policy that requires a medical exam. Do I have options?"
Yes. Depending on your health and financial goals, there are options that integrate long-term care features without requiring traditional medical exams or separate underwriting. During our initial consultation, we can walk through which of these structures may be appropriate for your situation.
Is there a cost to talk with someone?
No. The initial consultation is free, with no obligation, and we're not going to push you toward one specific product.
How much can long-term care actually cost?
It can be a significant retirement expense. According to Genworth's 2025 Cost of Care Survey, the national median annual cost was approximately:
- $80,080 for non-medical home care
- $74,400 for assisted living
- $114,975 for a semi-private nursing-home room
- $129,575 for a private nursing-home room
Actual costs can vary substantially based on where you live, the type of care you need and how long you need it.
When should I consider buying long-term care insurance?
There isn't one age that is right for everyone. The decision generally depends on your age, health, financial resources, retirement goals and ability to comfortably afford the premiums.
Many people begin exploring coverage in their 50s or 60s, when they may still be healthy enough to qualify and have many years of retirement planning ahead. Waiting can have consequences, however. Health changes can affect your ability to qualify for coverage or the terms available to you.
The important question isn't simply "Am I old enough?" It's "Does planning for long-term care make sense for my financial situation?"
What if I never need long-term care?
That's an important question — and one reason it's worth looking beyond traditional long-term care insurance.
With a traditional LTC policy, you're primarily purchasing protection against the risk of needing care. If you never use the benefits, the policy generally does not provide a death benefit simply because you didn't need care. Other strategies can work differently. Certain hybrid life insurance/LTC policies can provide long-term care benefits if you need them while also providing a death benefit if you don't.
The trade-offs — including premiums, benefits, guarantees, liquidity and death benefits — need to be evaluated carefully.
What if I already have substantial retirement assets?
Having significant assets doesn't necessarily mean you don't need long-term care planning.
In fact, the more you've accumulated, the more important it may be to understand how a prolonged period of care could affect your retirement income, spouse, estate and legacy goals.
Some people with substantial assets choose to self-insure, meaning they plan to pay for care from their own resources. Others use insurance to transfer some of the risk to an insurance company. Still others use a combination of insurance and personal assets.
There isn't a universal answer. The question is how much of the risk you are comfortable retaining and how much you would prefer to transfer.
Is traditional long-term care insurance the only option?
No. Traditional long-term care insurance is only one approach.
Depending on your circumstances, you may want to consider a number of options, sometimes used in concert with one another, because each approach has different costs, benefits, liquidity considerations and potential estate implications.
What happens if I have existing health issues?
Your health can be an important factor when applying for long-term care insurance because insurers generally evaluate your health during underwriting.
Certain health conditions or medical histories may make coverage more difficult or expensive to obtain, and some applicants may not qualify. That's one reason it can be useful to explore your options before a significant health event occurs.
If you already have health concerns, that doesn't necessarily mean you have no options. Different insurers and types of coverage can have different underwriting requirements, so your situation should be evaluated individually.
The sooner you understand your options, the more informed your decision can be.
You or a loved one has spent
decades building financial security.
Let's build a plan to protect it.
Ivory Johnson is a registered representative of Vanderbilt Securities LLC and an investment advisor representative of Consolidated Portfolio Review. Delancey Wealth Management and Vanderbilt Financial Group are separate and unaffiliated entities. Vanderbilt Financial Group is the marketing name for Vanderbilt Securities, LL and its affiliates. Securities offered through Vanderbilt Securities, LLC. Member FINRA, SIPC. Registered with MSRB.
Advisory services offered through Consolidated Portfolio Review. For additional information on services, disclosures, fees, and conflicts of interest,
please visit www.vanderbilttg.com/disclosures